Almost every plan you'll compare, whether on the marketplace or in the private market, is built around one of two network structures: PPO or HMO. The names get thrown around constantly, but most people I talk to know the acronyms without knowing what actually changes day to day. It's worth understanding before you're staring at a renewal packet, because the difference shows up in exactly the moments you'd rather not be figuring it out for the first time — an urgent specialist referral, a hospital stay out of state, a second opinion you want on your own terms.
The basic tradeoff
An HMO (Health Maintenance Organization) generally requires you to pick a primary care physician and get a referral from them before seeing a specialist. Care outside the plan's network typically isn't covered at all, except in a true emergency. A PPO (Preferred Provider Organization) skips the referral requirement and covers out-of-network care too, usually at a lower reimbursement rate than in-network care. That flexibility is why PPOs tend to carry a higher premium, and why HMOs can offer a lower one — you're trading choice and convenience for a narrower, more coordinated network.
Where an HMO earns its lower price
If you're generally healthy, see the same one or two doctors, and don't travel much for work, an HMO's restrictions may never actually cost you anything in practice. The lower premium is real, and for the right household it's not a compromise — it's just a better match for how they use care. The catch is that it requires your network to actually include the specialists you might need later, which is easy to overlook when you're healthy and not thinking about it.
Where a PPO earns its higher price
A PPO makes more sense if you split time between two states, want the option to see a specialist without waiting on a referral, or simply don't want your plan dictating who you're allowed to see. Business owners and self-employed clients tend to lean this way, since their schedules and travel patterns are less predictable than a typical W-2 employee's. It's a higher monthly cost for optionality you may or may not use in a given year — which is a reasonable trade for some households and an unnecessary one for others.
The network structure matters more than the acronym — what you're actually paying for is how much say you keep over who treats you.
Why this looks different once you're shopping the private market
On the ACA marketplace, plan structure is often secondary to subsidy eligibility — the math there is largely about income, not network preference. If you're above the subsidy threshold and reasonably healthy, though, you're shopping a different set of private-market plans, and PPO versus HMO becomes one of the more consequential choices you'll make, not a footnote. It's also one of the details that's easy to get wrong on your own, since plan names and marketing language don't always make the network type obvious at a glance.
How to actually decide
Start with how you actually use care, not with which option sounds more comprehensive. If you haven't needed a specialist in years and have a stable primary doctor, the HMO's lower premium is worth a real look. If you value flexibility, travel, or want a standing option to get a second opinion without a referral, the PPO's cost is buying you something specific. Either way, this is a plan detail worth reviewing every year rather than assuming it hasn't changed — networks shift, and a plan that fit your situation two years ago may not fit it now.
If you want help sorting through what your current plan actually offers versus what else is available, I'm at 864-689-4334.
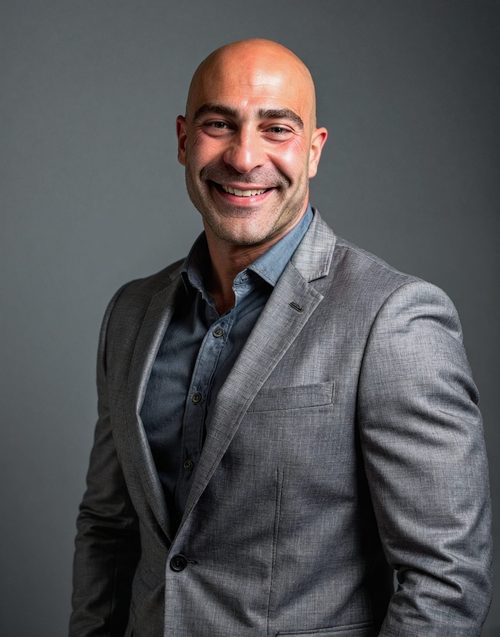
Isaac Dakar
Licensed life & health insurance broker, NPN #17433701. Licensed in 36 states.
This blog is intended for general, anecdotal informational purposes only and does not constitute insurance, financial, legal, or tax advice. It does not imply a guarantee of coverage, benefits, or eligibility. Insurance products, policies, pricing, and regulations vary by carrier and by state — consult a licensed agent about your specific situation before making any coverage decision.